The European wood-based panels sector is at a “crossroads” due
to challenges from low demand, increased costs, regulatory
burdens, and growing cheap product imports from China, delegates
were told at a major industry conference in Hamburg on October
14-16.
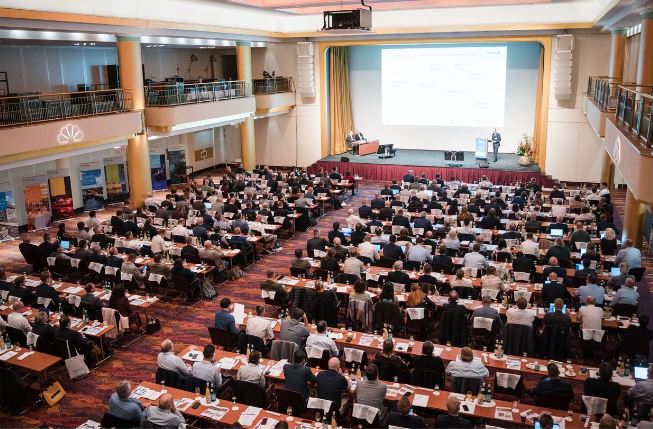
About 300 participants attended the 14th European Wood Based
Panels Symposium, organised by the European Panel Federation (EPF)
and research institute Fraunhofer WKI, with rumours of industry
consolidation and capacity adjustments being main talking points
among delegates.
Philipp Sprockhoff, EPF managing board member, said the European
wood-based panels sector was “at a crossroads”.
He said European wood-based panels production had grown 3% in
2025 but added that imports had increased by 6% – double the
rate of demand. Sprockhoff also highlighted energy and raw
material costs as a risk to Europe being uncompetitive as a
producing region compared to other global areas.
“Our trade defence system worked with Chinese hardwood plywood
imports [EU anti-dumping duties were introduced],” he said. “But
then the Chinese slightly modified products to dodge the
regulations by technicalities. Russian and Belarusian birch
plywood also circumvented rules by going through other countries
such as Egypt and Kazakhstan.”
Mr Sprockhoff also cited the “huge” €1.8bn cost of the EUDR
being implemented in the wood industries, and the recent
inclusion of urea under CBAM (Carbon Border Adjustment
Mechanism) as major industry challenges.
Thomas Walther, of AFRY Management Consulting, gave a 2027
market outlook where he highlighted shifts in global trade.
Walther said strong recovery momentum in Western European panels
markets was not expected before “late 2027”. The European WBP
industry is expected to focus on resilience, cost reduction, and
increasing use of recycled wood in board content, he added.
Due to the prolonged slump in panel demand in Western Europe,
Walther said a long-overdue reduction in capacity is expected.
“The question is – when will it be corrected?”
“A recovery of demand will definitely help, but our
forecasting models don’t see the levels of 2021 coming back
until 2030.”
AFRY’s baseline forecast is for slow normalisation.
Edi Snaidero, president of the European Furniture Industries
Confederation, which represents companies with a collective
annual turnover of approximately €100bn, produced one of the
event’s key moments when he shared details about his visit to
four Chinese furniture factories in May this year.
“What I saw shocked me,” he said. “There was a high level of
automation, with lines of 100 robots and use of AI, which is not
used as much in Europe, and they are helped by government
subsidies. Europe is a 500-million-person market for them – we
have the largest furniture market in the world, but we are not
defending it.”
He also cited US tariffs as shifting some Chinese furniture
exports from the US to Europe.
“Chinese furniture imports to Europe rose by 8% in value and 14%
in volume terms in 2025.”
“We are already in the storm,” commented Snaidero. “It is
important the industry stays united and speaks with a single
voice. No one company can do this alone.”
Snaidero argued for trade action to defend the interests of the
European furniture manufacturing sector.
Other key topics at this year’s Symposium included environmental
issues, timber construction, AI use in the panels sector,
recycling and resins.
Source:
ttjonline.com


