Even as, in advance of Labour Day, the North America construction framing
dimension softwood lumber market was in the usual snoozy mode, the price of
benchmark lumber commodity item Western S-P-F 2×4 crested higher than the
same week last year. And landed quite a bit above the same time in 2024.
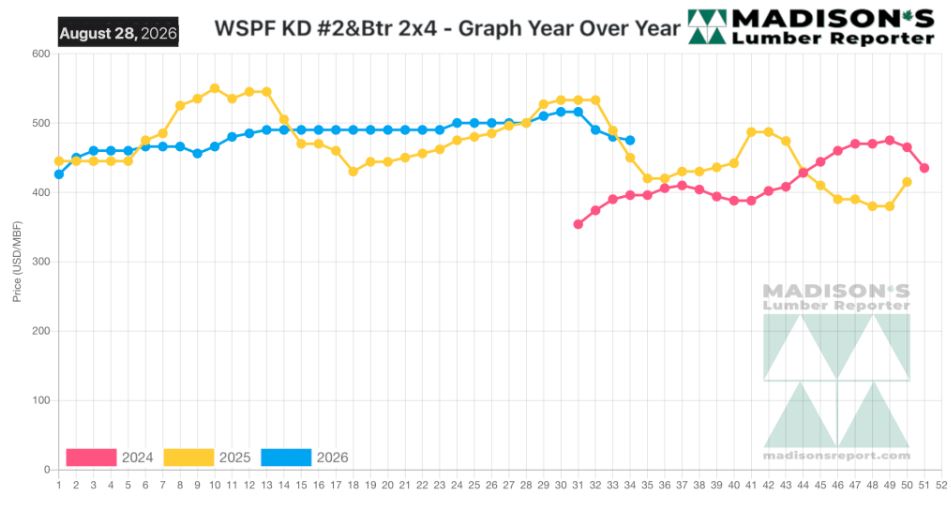
This nice even trend line over the course of two entire years provides a
good stability for sawmills in Canada and the US to see where the market is
and make their plans for the next upcoming new home building season in
spring of 2027.
In that time, the high for this item was US$550 mfbm in mid-March 2025, and
the low was $388 in October 2024.
A spread of $162 is a bit higher than historical over the course of a year,
but is still much less volatile than the recent several years.
In essence: this development provides a baseline for industry to know the
range of price high vs price low that will be likely going forward.
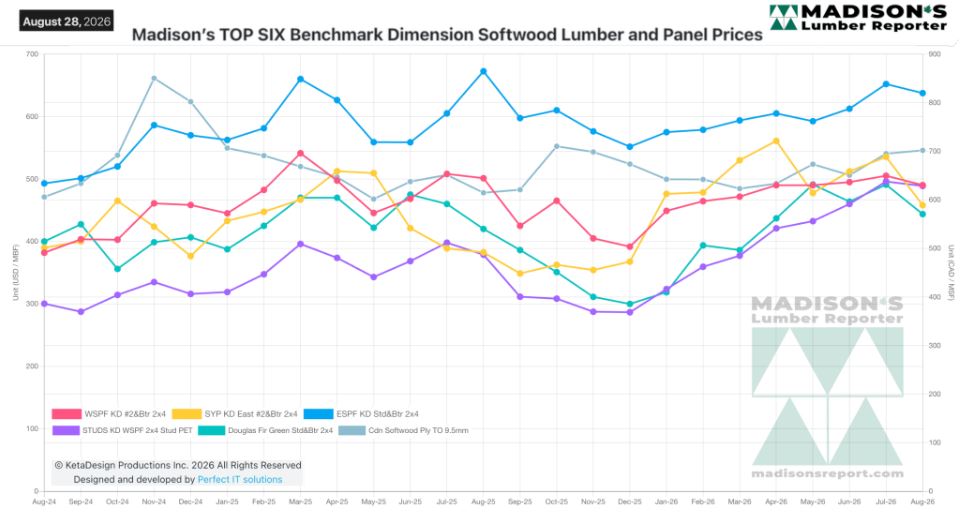
In the week ending August 28, 2026, the price of benchmark softwood lumber
item Western Spruce-Pine-Fir 2×4 #2&Btr KD (RL) was US$475 mfbm. This was
down -$5, or -1%, from the previous week when it was $480, said weekly
forest products industry price guide newsletter Madison’s Lumber Reporter.
That week’s price was down -$30, or -6%, from one month ago when it was
$505.
Compared to the same week last year, when it was US$450 mfbm, the price of
Western Spruce-Pine-Fir 2×4 #2&Btr KD (RL) for the week ending August 28,
2026 was up +$25, or +6%.
Compared to two years ago when it was $396, that week’s price was up +$79,
or +20%.
The latest trade salvo between the US and Canada become a hot topic of
conversation in an otherwise slow late-summer week.
 KEY TAKE-AWAYS:
• Western-SPF players in the US were more interested in taking the symbolic
last weeks of summer to vacation rather than sit at a desk.
• Trading activity unsurprisingly sputtered as distractions abounded ahead
of the upcoming Labour Day weekend holiday.
• Prices of Western-SPF in Canada continued its sideways-to-down drift as
summer holidays again took precedence over slow business.
• Scores of Eastern-SPF buyers staying out of the fray while a smaller
cohort opportunistically sniped discounted orders where they could be found.
• Higher-priced Euro wood was arriving into a much softer market, so the
next 30-45 days will be interesting.
• Southern Yellow Pine sawmills did a good job over the past few weeks
cleaning up accumulations of certain items.
• Alternating hot and stormy weather in the US northeast was not expected to
break until around mid-September, which kept construction activity there
low.
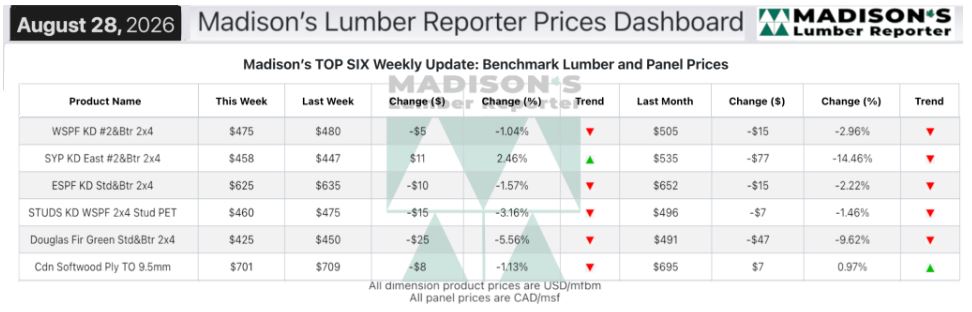
MADISON’S BENCHMARK TOP-SIX SOFTWOOD LUMBER AND PANEL PRICES: MONTHLY
AVERAGES
Source: madisonsreport.com
More Reports:


