As the usual slow-down to construction framing dimension softwood lumber
sales occurred into late September, the situation of severely-strained
inventories continued.
It seemed like most folks were just waiting for the year to actually wind
down into winter, and did not want to change their practice of not loading
up their yards with wood. The now multi-year habit of just-in-time buying
seems to have become entrenched.
While demand was low enough to justify this, the burgeoning situation of
sharply-rising fuels costs started causing real problems.
Customers who were satisfied with the sales prices abruptly balked when the
cost of fuel surcharges were added to their orders. Expect this to become a
regular occurrence, as diesel prices will indeed rise further into the
beginning of 2027.
The next unknown is the arrival of storm season in the US, and what that
will mean for property destruction thus rebuilding. There have been times in
the past when re-roofing activity during December was high enough to prop up
lumber sales somewhat.
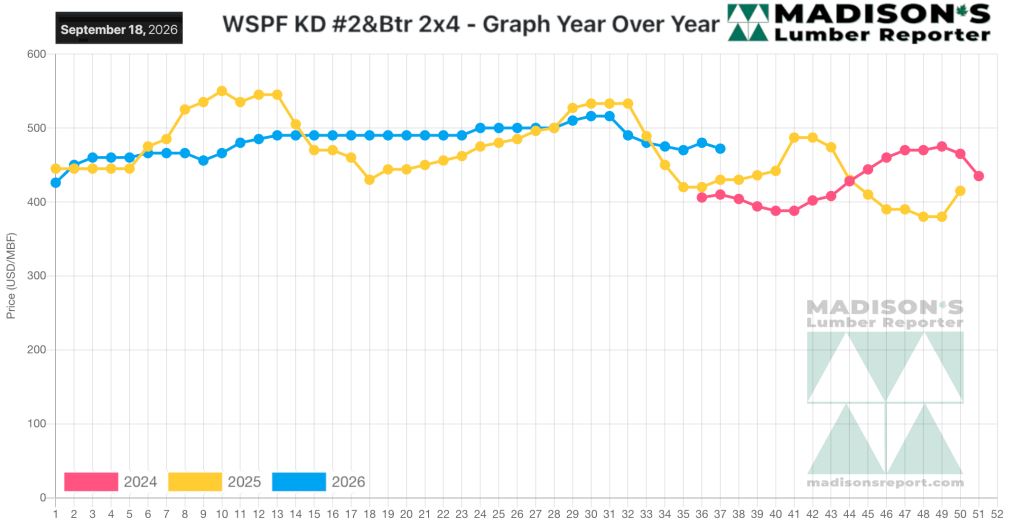
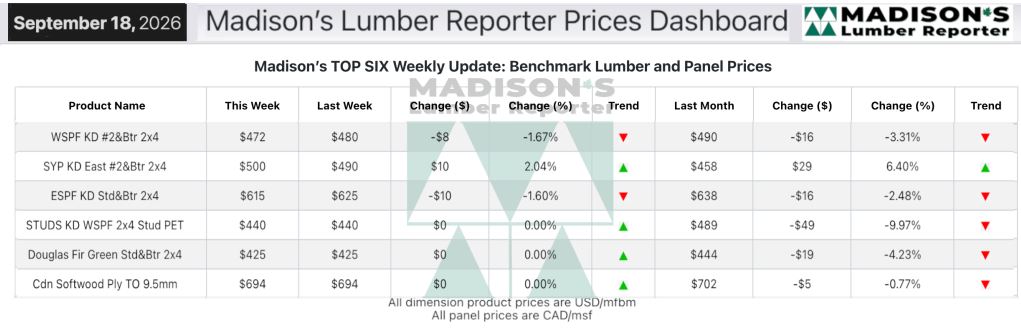
In the week ending September 25, 2026, the price of benchmark softwood
lumber item Western Spruce-Pine-Fir 2×4 #2&Btr KD (RL) was US$464 mfbm. This
was down -$8, or 22%, from the previous week when it was $470, said weekly
forest products industry price guide newsletter Madison’s Lumber Reporter.
That week’s price was down -$26, or -5%, from one month ago when it was
$490.
Compared to the same week last year, when it was us$430 mfbm, the price of
western spruce-pine-fir 2×4 #2&btr kd (rl) for the week ending September 25,
2026 was up +$34, or +8%.
Compared to two years ago when it was $404, that week’s price was up +$60,
or +15%.
Ongoing challenges for the SPF and Hemlock/Douglas fir species were widely
reported. Meanwhile, a supply-driven surge helped OSB break out.
 KEY TAKE-AWAYS:
• According to Western-SPF traders in the United States, there was minimal
lumber inventory on the ground with all suppliers.
• Business was largely relegated to specific prompt tallies with verifiable
delivery costs and timelines.
• Logistical hurdles continued to plague suppliers, with some sawmills
struggling to find carriers due to fuel prices.
• Purchasers often walked away from attractive sawmill pricing once freight
costs were factored in.
• Many customers didn’t have negotiating freedom as they had let their
inventories run down to bare pavement.
• Canadian Western-SPF sellers continued to search for stable levels on a
few key items, while most dimension widths’ prices remained flat.
• Eastern-SPF players cautioned there was plenty of variation between mill
pricing, and numbers were often not aligned with print.
• Most Southern Yellow Pine prices deviated palpably from print as patient
buyers found deals by shopping around between suppliers.
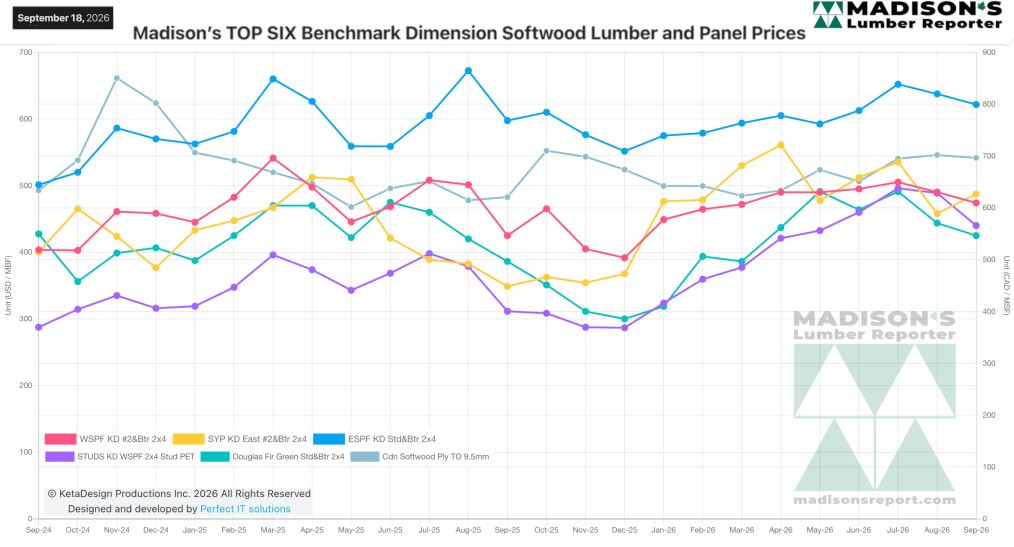
MADISON’S BENCHMARK TOP-SIX SOFTWOOD LUMBER AND PANEL PRICES: MONTHLY
AVERAGES
Source: madisonsreport.com
More Reports:


