As October dawned the supply-demand situation for north america construction
framing dimension softwood lumber did not become any less murky.
What was absolutely clear was that delivery will be an ongoing hurdle into
the end of this year, at the least. The lack of available trucks and rail
cars continued, even with these lower lumber volumes, now the added
constraint of constantly rising diesel fuel prices made the process of
receiving wood previously ordered even more complicated.
The sales prices approached cost-of-production and couldn’t really go any
lower within the current economics. The added charge of transportation costs
was something the customers just had to bear.
Larger sawmill operators in the northwest had booked production into late
October
thus were unwilling to listen to counter-offers of any substantial amount.
Everyone was watching the weather; if it is a severe storm season that will
mean an increase in demand for panel, especially plywood, for repairs and
re-roofing.
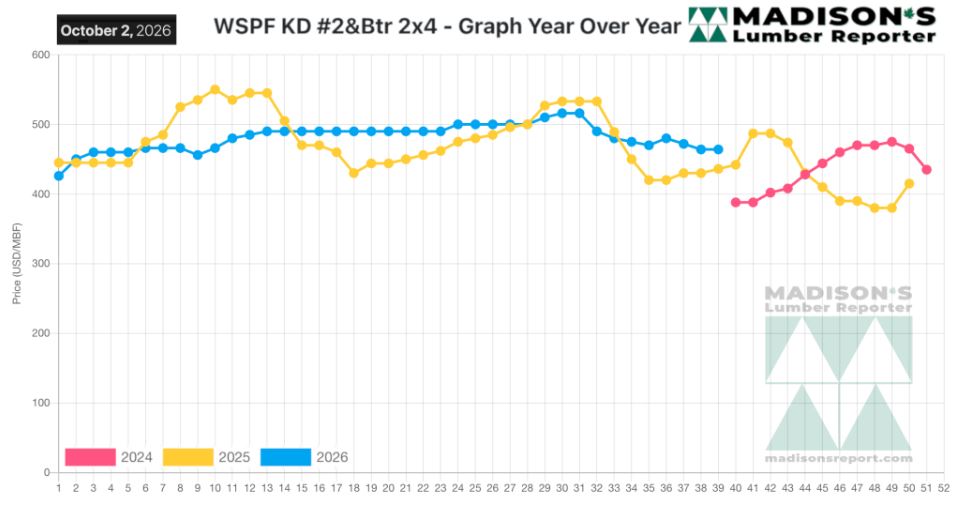
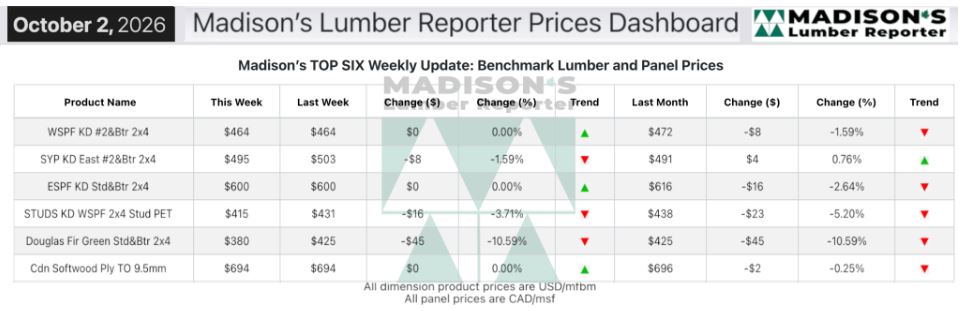
In the week ending October 02, 2026 the price of Western Spruce-Pine-Fir 2×4
#2&Btr KD (RL) was US$464 mfbm, which was flat from the previous week, said
weekly forest products industry price guide newsletter Madison’s Lumber
Reporter.
That week’s price was down -$8, or -2%, from one month ago when it was $472.
Compared to the same week last year, when it was us$436 mfbm, the price of
western spruce-pine-fir 2×4 #2&btr kd (rl) for the week ending October 02,
2026 was up +$28, or +6%.
Compared to two years ago when it was $404, that week’s price was up +$60,
or +15%.
Many categories of studs prices slid downward. Panels remained a
headscratcher, with OSB prices again showing uncharacteristic strength for
the time of year.
 KEY TAKE-AWAYS:
• Western lumber markets showed paradoxical signs of stable instability.
• Buyers of Western-SPF in the US continued to focus on their most
short-term needs only.
• Sawmills attempted to draw a line in the sand on their asking prices.
• Large Canadian Western-SPF mills leaned on order files into late October
and refused to budge on pricing.
• Logistics played a significant role with each order; freight costs and
timelines could make or break deals.
• Demand for Eastern-SPF came in fits and starts while prices were
relatively stable.
• Price vulnerability was apparent across the entire Southern Yellow Pine
complex.
• Southern US sawmills held tenuous lead times into early- or mid-October at
best.
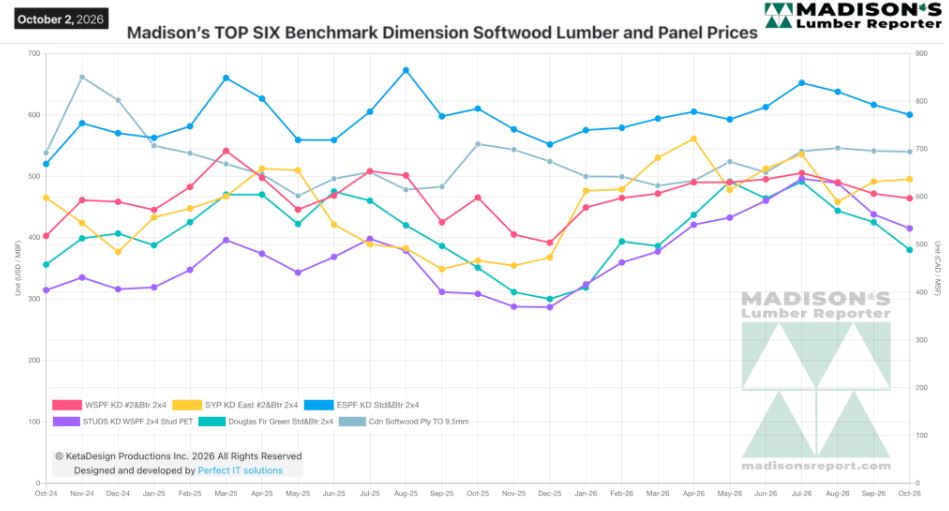
MADISON’S BENCHMARK TOP-SIX SOFTWOOD LUMBER AND PANEL PRICES: MONTHLY
AVERAGES
Source: madisonsreport.com
More Reports:


